Homeowners Insurance in Horizon West: New Construction vs Resale (and Flood Basics Buyers Ask About) (2026)
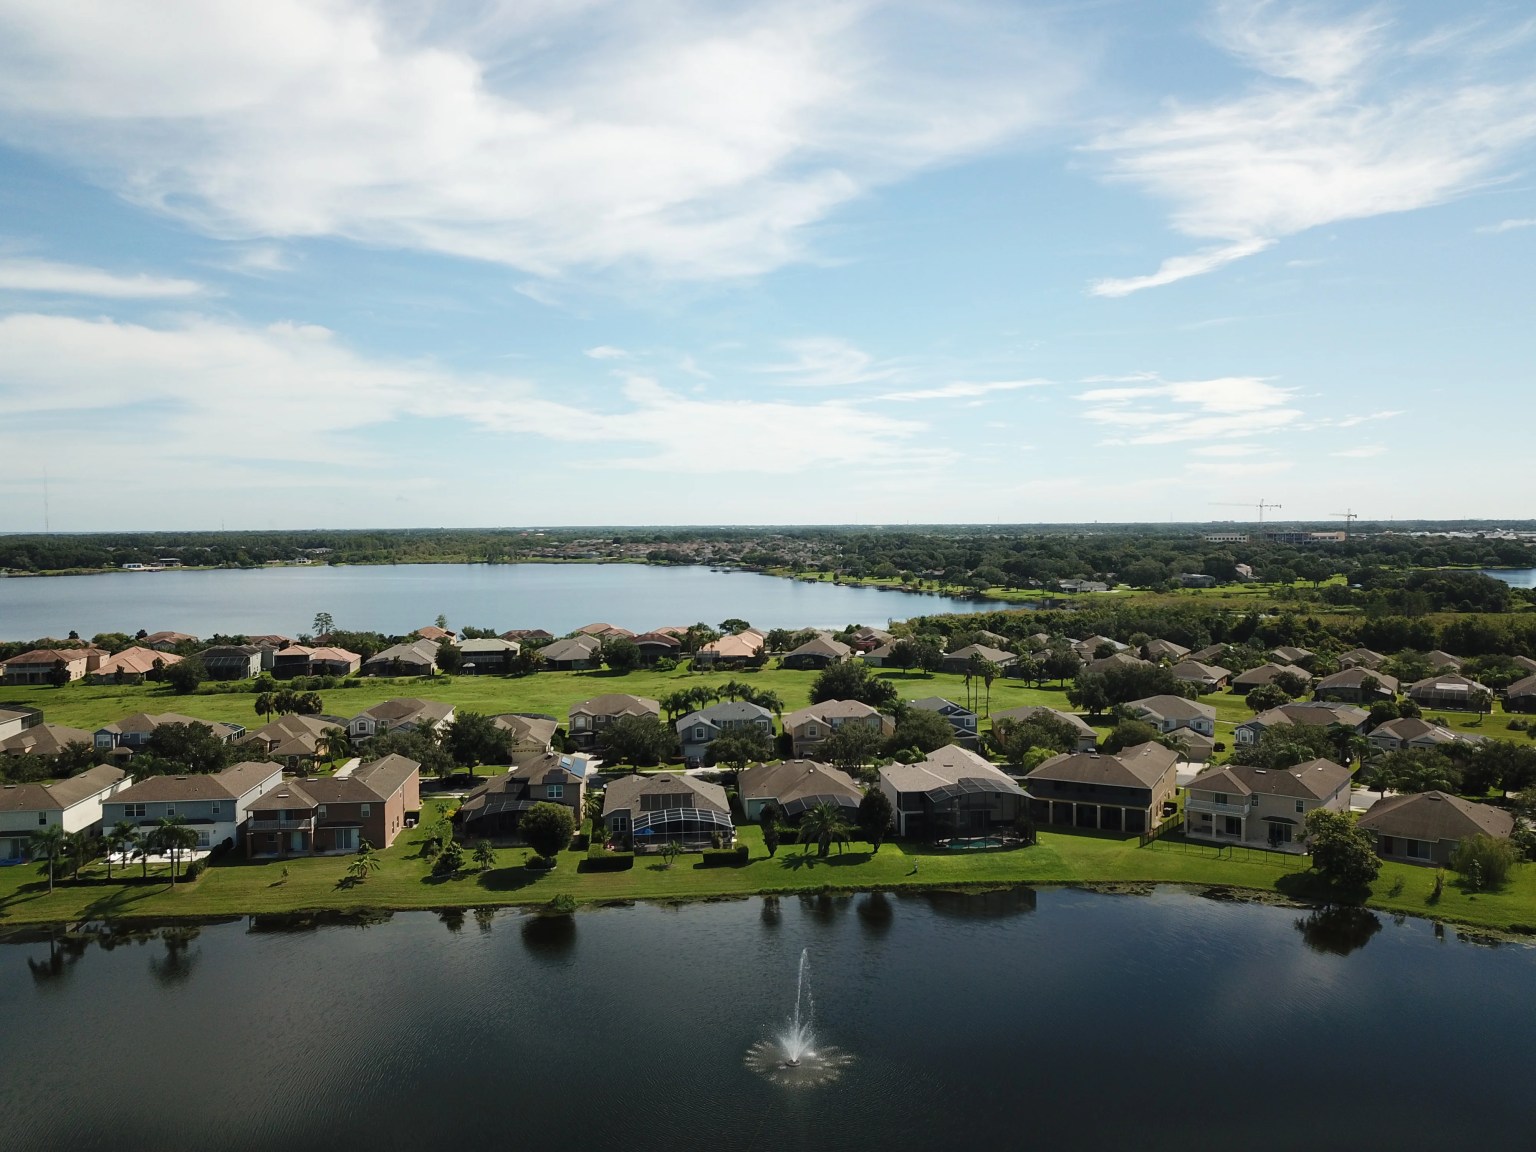
Lakefront homes in the Horizon West area of Winter Garden, Florida.
Image: Jared Jones Team
Quick answer
Quote homeowners insurance on the specific address before you lock a rate, and check the FEMA Flood Map Service Center for that parcel (FEMA MSC, checked Oct 2026). Premiums vary by roof, construction, deductible and flood exposure — we do not publish sample dollar quotes here. Call or text 407-706-5000 and we will help you gather the docs insurers ask for.
| Fact | Figure | Source |
|---|---|---|
| Flood map lookup | Search the parcel address in FEMA’s Flood Map Service Center | FEMA MSC address search, Oct 2026 |
| Homeowners vs flood | Standard homeowners policies typically exclude flood; flood coverage is a separate decision | FEMA / NFIP education materials, Oct 2026 |
| New construction docs | Ask the builder for wind-mitigation, roof and construction details in writing before binding | Builder / insurer underwriting checklists |
| Resale docs | Request roof age, prior claims disclosures and any wind-mitigation inspection the seller has | Seller disclosures + licensed inspector |
| Sample premiums | Call or text 407-706-5000 for help lining up quotes on your shortlist addresses — we do not invent premium figures on this page | Jared Jones Team, Oct 2026 |
What drives premiums on new construction vs resale?
Insurers price from the property file: construction type, roof age and material, distance to coast or other underwriting factors, deductibles, claims history and available mitigation credits. A brand-new Horizon West build and a ten-year-old resale a few streets away can quote very differently even at similar list prices.
On new construction, get the builder’s written specs and any wind-mitigation or elevation paperwork early so your agent can shop carriers with complete files. On resale, pull roof age, prior claims disclosures and a current inspection before you treat a quote as final. For how new builds and resales differ in the deal itself, see our buyer’s agent guide and new construction overview.
How do I check flood zone for a parcel?
Enter the full address in the FEMA Flood Map Service Center and review the effective Flood Insurance Rate Map panel for that location. Save or print the result with the date you checked it. Flood maps can be updated, so re-check before closing if time has passed since your first search.
A flood-zone designation is not the same as a homeowners premium quote, and standard homeowners coverage typically does not pay flood claims. Ask your insurance agent whether a separate flood policy makes sense for that parcel after you have the FEMA map in hand.
What about roofs and wind mitigation docs?
Roof age, roof material and documented wind-mitigation features often affect Florida homeowners pricing. On resale, ask for any existing wind-mitigation inspection and confirm roof age in the disclosure package. On new construction, ask the builder which documents your insurer will need before the policy can bind.
Have a licensed inspector or your insurance agent confirm what credits apply — do not assume a model-home brochure equals underwriting credit. If a seller or builder cannot produce a document you need for quotes, get that gap in writing before you remove financing contingencies.
How do CDD and HOA relate (or not) to insurance?
CDD assessments and HOA dues are ownership costs that show up on tax bills and association documents; they are not the same as a homeowners or flood premium. Still, buyers should stack all of them when comparing true monthly cost. Use our Horizon West CDD fees guide and HOA fees guide for the fee lookup process.
Some associations carry master policies for shared buildings or amenities; that does not replace the dwelling policy you need on a typical single-family home. Ask in writing what the HOA covers and what remains on your personal policy.
What should buyers get in writing before locking a rate?
- A dated FEMA flood-map check for the exact address.
- Roof, construction and wind-mitigation documents the carrier requested.
- At least two homeowners quotes on matching coverages and deductibles.
- A clear note on whether flood coverage is included, excluded or quoted separately.
- Any HOA master-policy summary that affects what you must carry.
Premium dollars change with market conditions and underwriting. Call or text 407-706-5000 and we will help you assemble the file for the Horizon West addresses on your shortlist.
Frequently asked questions
Does homeowners insurance cover flood damage in Horizon West?
Usually not. Standard homeowners policies typically exclude flood. Check the parcel on the FEMA Flood Map Service Center, then ask your insurance agent whether a separate flood policy fits that address. Call or text 407-706-5000 if you want help gathering the map and docs for your shortlist.
Are new-construction premiums always lower than resale?
Not always. Carriers price from roof, construction, deductibles, claims history and mitigation documentation. A new build can quote lower or higher than a nearby resale depending on the file. Compare written quotes on matching coverages before you decide.
Where do I look up the flood zone for an address?
Use FEMA’s Flood Map Service Center address search, enter the full street address, and save the effective map result with the date checked. Re-check before closing if time has passed since your first search.
What documents should I request from a builder for insurance?
Ask in writing for construction specs, roof details and any wind-mitigation or elevation paperwork your insurer needs to bind coverage. Incomplete files delay quotes, so collect them before you treat a rate as final.
Do CDD fees include homeowners insurance?
No. CDD assessments are separate non-ad valorem charges on the tax bill. HOA dues and insurance premiums are also separate. Stack all three when you estimate true monthly cost.
Can you help me get insurance quotes?
We do not invent premium figures on this page. Call or text 407-706-5000 and the Jared Jones Team can help you assemble address docs, FEMA map checks and the questions carriers typically ask so your agent can quote accurately.
Sources
- FEMA Flood Map Service Center, checked Oct 2026
- FEMA / National Flood Insurance Program education materials, Oct 2026
- Horizon West CDD Fees 2026 (method cross-link)
- HOA Fees Winter Garden & Horizon West 2026 (method cross-link)
- Jared Jones Team, Brokered by eXp Realty, 2026
Related Wave 1 guides
Buying or selling in Winter Garden or Horizon West?
Get street-level pricing, an honest commute read and a clear plan to close. Call or text 407-706-5000.