
Why Are Orlando Builders Cutting Prices and Offering Incentives in 2026?
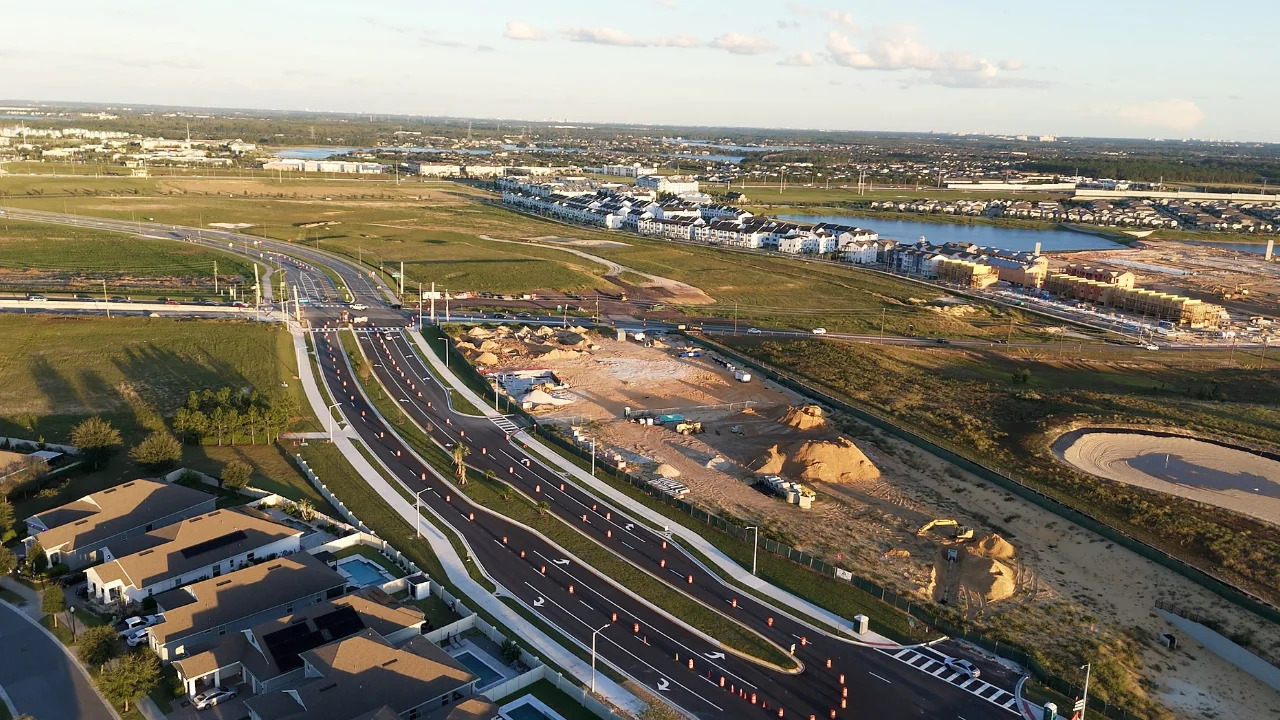
Photo: jaredjones.com
Quick answer
As of November 2026, many are. NAHB’s September survey found 38% of builders cut prices, by 6% on average, and 66% used incentives; that share rose to 43% in October. The Census Bureau counted 8.5 months of new-home supply in August 2026.
| Fact | Figure |
|---|---|
| NAHB, September 2026 | 38% cut prices, 6% average cut, 66% used incentives |
| NAHB, October 2026 update | 43% cut prices |
| Census Bureau, August 2026 | 8.5 months of new-home supply |
| Lennar, third quarter 2026 | About 12% incentives in the average sales price |
| PulteGroup, Q2 2026 (national) | Options and lot premiums near $107,000 per home |
| Freddie Mac 30-year average | 7.28% the week of Oct. 1; 7.11% as of Nov. 12, 2026 |
Sources: NAHB Housing Market Index, September and October 2026; U.S. Census Bureau, New Residential Sales, August 2026; Lennar third quarter 2026 results; PulteGroup Q2 2026 earnings call; Freddie Mac Primary Mortgage Market Survey (all checked Nov 13, 2026). Local markdown examples in the video are Jared’s observations, not a formal survey.
Why are builders cutting prices right now?
Payments are still heavy. When Jared recorded the video, Freddie Mac’s 30-year average had reached 7.28% the week of October 1, 2026, the highest reading since November 2023. By November 12 it had eased to 7.11%, which still leaves a much higher payment than buyers saw a few years ago. When payments rise, some buyers pause, and finished inventory starts to cost the builder money.
The national supply number helps explain the urgency. The Census Bureau counted 8.5 months of supply of new homes for sale in August 2026. A finished quick move-in home that sits is a carrying cost, which is why list-price cuts and other incentives show up first on homes that are already built.
How common are incentives, and how large are they?
They are widespread. NAHB’s September 2026 survey found that 38% of builders cut prices, by 6% on average, and 66% used incentives. In the October update, the share cutting prices rose to 43%. Those are national survey figures, not an Orlando-only census, but they match what Jared is seeing on local builder lists.
Large public builders are also openly reporting the cost of those deals. Lennar said its average sales price in the third quarter of 2026 reflected about 12% in incentives. In the video, Jared said most homes on recent quick move-in lists he reviewed were marked down around $25,000, with select townhomes in one community averaging as much as $57,000 off the advertised price. Those local figures are his observations, and this page does not name the communities.
What sits on top of the base price?
The advertised base price is only the starting line. Lot premiums, design-center options and local impact fees can push the final number well above it. PulteGroup said options and lot premiums on the homes it closed in the second quarter of 2026 approached $107,000 per home. That is a national figure, not a Central Florida average, but it shows how large those add-ons can be.
In unincorporated Orange County, school and transportation impact fees alone run roughly $19,000 to $23,000 for a 2,000-square-foot single-family home, depending on the district, before parks, fire and law enforcement fees. Florida also requires a bold CDD disclosure in the sales contract for the first sale of a home in a community development district. Ask for the total monthly payment, including estimated taxes, CDD and HOA, not just the sticker.
How is a quick move-in markdown different from other incentives?
A price cut on a finished home reduces the contract price, which reduces the loan amount for the life of the mortgage if you keep that principal. Other incentives, including temporary rate buydowns, options credits and closing-cost help, can lower the cash needed now without changing the price in the same way. Which one is stronger depends on how long you will keep the loan and what the Loan Estimate actually shows.
If the choice in front of you is a buydown versus a price cut, use our separate guide on that comparison, including Fannie Mae’s 3% to 9% interested-party contribution caps and FHA’s 6% cap. This page will not repeat that math. The practical step is the same either way: put both offers on a Loan Estimate and compare the total cost, not the advertised rate or the sign in the yard.
How should you read a builder’s offer in this market?
Ask how many finished homes are left in that community, how long the builder expects to keep selling there, and what is included in the price being quoted today. Incentives can change from week to week, and a rate in an ad may not be the rate on your Loan Estimate. If a payment example is used, confirm the down payment, the term, the points and whether the rate is temporary.
Then look past the house itself. A lower sticker can still lose to a nearby resale once lot premiums, CDD assessments and taxes are included, or it can still be the stronger choice if the markdown is real and the home is otherwise a fit. Bring the offer to an agent who is working for you, not only to the salesperson in the model home.
Have questions about buying or selling here? Call or text 407-706-5000 or visit jaredjones.com.
Jared Jones Team, Brokered by eXp Realty.
Frequently asked questions
Does a national NAHB number mean every Orlando builder is cutting prices?
No. The September and October 2026 NAHB figures are national survey results. They tell you that price cuts and incentives are common, not that every community in Central Florida has the same markdown. Jared’s local examples, including the roughly $25,000 quick move-in cuts and the $57,000 townhome average he cited, are his observations from lists he reviewed. Always verify the offer on the specific community and home.
Is a 12% incentive the same as a 12% price cut?
Not necessarily. Lennar said its third-quarter 2026 average sales price reflected about 12% in incentives, which can include price reductions, rate buydowns, options credits and other concessions. Those items do not all have the same effect on your loan balance or your payment after year one. Ask the builder to itemize what is in the 12%, then compare it on a Loan Estimate.
Why would a builder rather offer a buydown than cut the price?
A temporary buydown can make the early payment look lower while leaving the contract price higher. That can help the builder’s comparable sales and the appraised value on later homes. It may or may not be the stronger deal for you, depending on how long you keep the loan. Our buydown versus price-cut guide walks through that comparison, including loan-limit caps on builder-paid buydowns.
Do lot premiums and upgrades show up in the list price?
Often they do not. The advertised base price may be for a standard lot and a standard finish level. PulteGroup’s national second-quarter 2026 figure, with options and lot premiums approaching $107,000 per home, is a reminder to ask for a net sheet that includes the lot, the options you actually want and the estimated taxes, CDD and HOA. A low base price can disappear once those items are added.
Should you skip resale homes just because builders are discounting?
No. A markdown can close some of the gap, but it does not automatically make a new home cheaper than a nearby resale once taxes, CDD fees, lot premiums and commute are included. Our Horizon West new-construction versus resale guide looks at that tradeoff in more detail. Compare the monthly payment and the total cost of ownership, not only the sign in front of the model home.
Can a builder’s advertised rate change before you close?
Yes. An advertised rate is not a lock unless you have a lock in writing from the lender, with dates and conditions. Temporary buydowns can also expire after one to three years, at which point the payment rises. Read the Loan Estimate, confirm whether the rate is temporary, and do not rely on a social media ad or a roadside sign as the final number.
Sources
- NAHB: September 2026 Housing Market Index (38% cut prices, 6% average, 66% used incentives; checked Nov 13, 2026)
- NAHB: Housing Market Index, October 2026 update (share cutting prices rose to 43%; checked Nov 13, 2026)
- U.S. Census Bureau: New Residential Sales, August 2026 (8.5 months of new-home supply; checked Nov 13, 2026)
- Lennar: third quarter 2026 results (about 12% incentives in the average sales price; checked Nov 13, 2026)
- PulteGroup: Q2 2026 earnings call transcript (options and lot premiums approached $107,000 per home, national figure; checked Nov 13, 2026)
- Freddie Mac: Primary Mortgage Market Survey archive (7.28% week of Oct. 1, 2026; 7.11% as of Nov. 12, 2026; checked Nov 13, 2026)
- Fannie Mae Selling Guide: interested party contributions (3% to 9% caps by down payment; checked Nov 13, 2026)
- Orange County: impact fees at a glance (school and transportation fees on a 2,000 sq ft home; checked Nov 13, 2026)
- Florida Statutes s. 190.048 (bold CDD disclosure in the initial sales contract; checked Nov 13, 2026)
- Jared Jones – Orlando Living (YouTube): Orlando Builders Are Slashing Prices (That’s Not All!) (published Nov 9, 2026)
Related guides
- Winter Garden & Horizon West Real Estate (2026): Buy, Sell and Invest Hub
- Is a Builder Rate Buydown a Better Deal Than a Price Cut in Orlando? (2026)
- What Should You Know Before Buying New Construction in Florida? (2026)
- New Construction vs Resale in Horizon West: Prices, Monthly Payment and Tradeoffs (2026)
- Do HOA Fees Go Up After the Builder Leaves a Florida Community? (2026)